Nigeria and other West African countries must shift from exporting raw materials and signing trade agreements to building industries that process local resources and create jobs, the President of the ECOWAS Commission, General Birame Diop, has said.
Diop said regional industrialisation and stronger value chains were essential to translating West Africa’s market potential into employment and economic prosperity, warning that trade agreements alone could not deliver the desired results without productive industries.
“Trade agreements do not create jobs; industries do,” he said.
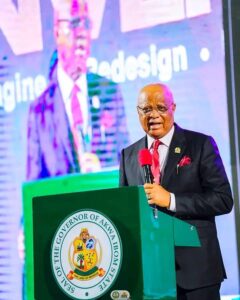
He spoke at the 32nd Nigerian Economic Summit in Abuja, themed “From Trade to Value Chains: Building Regional Industries to Compete Globally,” with the sub-theme “Invest Nigeria.” His remarks were delivered by the ECOWAS Commissioner for Economic Affairs and Agriculture, Hon. Dehpue Yenpea Zuo.
Diop noted that intra-African trade accounted for about 15 per cent, compared with more than 60 per cent in Europe and Asia, attributing the disparity partly to the limited scale of industrial production across African countries.
He identified the ECOWAS market of more than 300 million consumers as an immediate opportunity for Nigerian manufacturers to expand production, reduce costs through economies of scale and improve their competitiveness before entering the wider African market under the African Continental Free Trade Area.
The ECOWAS chief outlined four priorities for accelerating regional industrialisation: implementing existing agreements, including commitments relating to border operations; developing value chains in sectors where West Africa has competitive advantages; securing financing for businesses across the production chain; and measuring progress by jobs created and goods processed within the region.
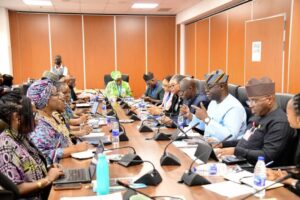
Also speaking at the summit, the Minister of State for Foreign Affairs, Ambassador Sola Enikanolaiye, called for stronger government-private sector partnerships and increased investment in young people to move Nigeria from a trading economy towards one driven by production and value addition.
Enikanolaiye said the government could not independently mobilise the resources required for sustainable economic growth, stressing the need to attract domestic and foreign capital through constructive engagement with businesses.
According to him, collaboration between the public and private sectors would help unlock investment, expand industrial capacity and create opportunities for shared prosperity.
The minister maintained that democracy must produce measurable improvements in citizens’ economic circumstances, arguing that governance should be assessed by its contribution to development and prosperity.
“Democracy is good, but it is a means to an end, not an end in itself. Democracy must deliver on core priorities of economic development and economic prosperity to our people,” he said.
Enikanolaiye also identified Nigeria’s youthful population as an important economic asset, urging greater investment in human capital, small and medium-sized enterprises, technology, innovation and creativity to expand employment and wealth creation.
He said improvements in macroeconomic stability and declining inflation would help businesses plan investments and operate in a more predictable environment.
The minister further reaffirmed the Federal Government’s commitment to its reordered 4D foreign policy doctrine, which prioritises Demography, Development, Democracy and Diaspora, with national interest and the welfare of Nigerians at its centre.
He said the Ministry of Foreign Affairs would continue strengthening engagement with Nigerian citizens and the private sector while using bilateral, regional and international partnerships to support investment and industrial development.
Enikanolaiye’s remarks followed his participation at the Berlin Global Dialogue, where, according to him, discussions highlighted the importance of investment and economic resilience amid global uncertainties.
Both officials underscored the need to connect trade with domestic production, regional manufacturing and job creation, with stronger financing and public-private cooperation identified as key requirements for building industries capable of competing in global markets.